

Why Now Is the Time to Pay Off High-Interest Debt With Your Home Equity

What the Data Says
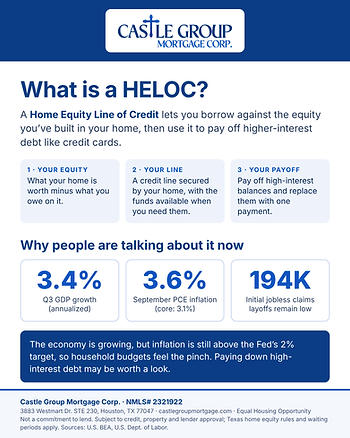
GDP grew 3.4% in Q3, up from 2.2% in Q2, driven by consumer spending (+3.8%) and business investment.
Inflation is still running hot. September headline PCE came in at 3.6% year over year, and core PCE at 3.1%. Both are well above the Fed's 2% target.
The job market is steady. Initial jobless claims fell to 194K, so layoffs remain low even as hiring slows.
The Fed is changing how it communicates. It will keep eight meetings a year. Starting in 2027, some will focus on broader policy discussion instead of rate decisions, with two per year in that format by 2028. The Fed is also giving less detailed guidance on future moves, which could mean bigger swings in Treasury yields around releases and announcements.
What It Means for Your Wallet
A strong economy doesn't automatically mean your household feels comfortable. Prices on everyday essentials are still elevated, and many families have leaned on credit cards to bridge the gap. Credit card balances often carry rates in the 20s, and that interest compounds month after month.
With less Fed guidance, rates may get harder to predict. Nobody can promise where borrowing costs go from here. What you can control is how much high-interest debt you carry while you wait.
Why a HELOC Can Make Sense
If you own your home, you may be sitting on equity that could replace expensive debt with something cheaper. A Home Equity Line of Credit (HELOC) can help you:
Consolidate high-interest balances. Use your equity to pay off credit cards, personal loans or other costly debt.
Keep your first mortgage as is. If you locked in a good rate, a HELOC sits behind it, so you don't have to refinance it.
Borrow only what you need. A line of credit gives you flexibility, and you pay interest only on what you use.
Move fast. Our process is built for speed. Many borrowers can get an approval decision in as little as 30 minutes and see funds in as little as 7 days.
Know the Tradeoffs
A HELOC is secured by your home, and most carry variable rates, so payments can change. It works best when you have a plan to pay the balance down and a commitment not to run the cards back up. We'll walk through the numbers with you, including how much you could save and whether it makes sense for your situation.
Let's See What It Could Save You
If you're carrying balances at high interest, a quick conversation could show you a better path. It takes a few minutes to find out if a HELOC fits.
Joseph CastilloOwner & Broker of Record, Castle Group Mortgage CorpNMLS# 2321922📧 jc@castlegroupmortgage.com | 🌐 castlegroupmortgage.com📍 3883 Westmart Dr. STE 230, Houston, TX 77402
*Approval and funding timelines vary by borrower and are subject to credit approval, property valuation, title and program requirements. Not a commitment to lend. HELOC rates are variable and your home secures the loan. Economic data cited is from recent public releases and is for informational purposes only.
Comments